
Article
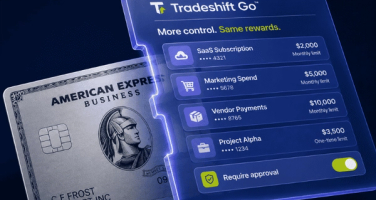
Tradeshift Go Review: How to Supercharge Your American Express Business Credit Card
Tradeshift Go adds virtual cards, approvals, and reporting on top of Amex business cards, no rewards traded away. This review covers use cases and dashboard.
Topic hub
Articles, videos, podcasts and webinars on Cash Flow for ecommerce brands.
Tradeshift Go adds virtual cards, approvals, and reporting on top of Amex business cards, no rewards traded away. This review covers use cases and dashboard.
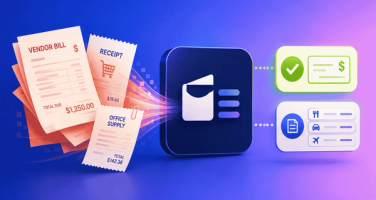
Paper bills and shoebox receipts are out. This roundup covers five apps for automating bill pay and expense tracking, from Bill.com to Veem, and what each does best.
Brex Cash is a bank alternative for startups: no fees, no minimums, near-instant access to revenue. This covers its features, protections, and who it fits.
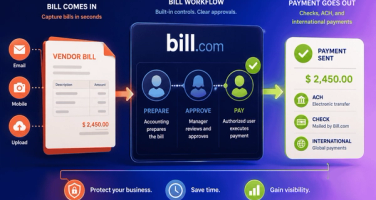
LedgerGurus reviews Bill.com as a certified partner: automated payments, built-in separation of duties, tight QBO integration, and who gets the most value.
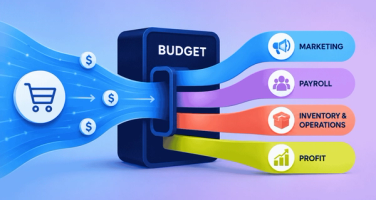
A budget turns financial guesswork into control. This walks through five steps to build one, from gross profit margin to monthly review and adjustment.
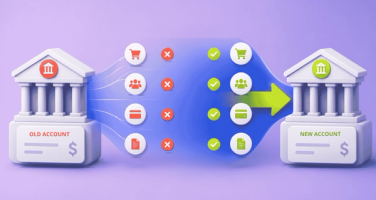
Switching banks touches more than expected: payroll, ACH, merchant accounts. This 10-step checklist covers what to look for and how to update every system.

Your P&L shows profit and your bank account does not agree. The cash conversion cycle explains the gap: how many days your money sits trapped in inventory and receivables before it comes back. Stephen Brown walks the three components and the math, contrasts Dell and Costco running near zero or negative cycles, and explains why most ecommerce brands run at least 90 days and some carry 240 days of inventory.

Shopify Capital lends a lump sum and takes repayment as a percentage of daily sales, with no credit check and no personal guarantee. Stephen Brown spoke to a Shopify Capital specialist, then walked through a real offer on a store he co-owns. The convenience has a price: roughly 9 to 15% effective APR against 7 to 9.5% on an SBA loan at the time, and faster repayment pushes the real rate higher.

The right bank changes as your business does. Stephen Brown maps three bank types onto three stages: neobanks or a big bank while you're small and want everything online, a regional bank or credit union once the cash cycle forces you to need a line of credit, and multiple banks once you're moving serious money internationally. He also makes the case that running more than one bank is normal, not a problem.
Guest: Samir Shergill, CEO and co-founder of Highbeam. A software engineer by trade, he spent years at Microsoft and then at ad tech startup AppNexus before acting as an informal CFO for friends' consumer brands. That work led him to build Highbeam, a banking and cash management platform built specifically for ecommerce.

Stephen Brown and Preston Alder have spent three years learning debt the hard way at Solé Toscana, including personal loans that took three years to repay. They cover why merchant cash advance pricing hides the real APR, why the paperwork-heavy loans are usually the good ones, and why they will take debt for inventory but not for unproven marketing. They finish with the cash flow levers most sellers overlook, from card float to renegotiated supplier terms.

Matthew Kidman came out of the 2000s Florida real estate market with tens of thousands in credit card debt and two years of splitting entrees to pay it off. House of Joppa has never taken any. He tells Stephen Brown how that works across 400 to 500 SKUs and 50 suppliers: deliberately lean inventory, staged supplier payments, stockouts treated as acceptable, and cash held as a constraint rather than a problem to be solved.
There is a mathematical limit to how fast an inventory business can grow on its own profits, and most owners have never calculated theirs. Stephen Brown walks through the cash conversion cycle, turns it into a working capital intensity ratio, and divides profit margin by that ratio to produce the ceiling. For a typical brand with a 5% net margin and a 150 day cycle, that ceiling lands around 12%. He then covers the three levers that raise it.

A purchase order from Whole Foods or Walmart sets off labels, packaging, freight bills, work orders, and 3PL transfers, all funded before a dollar comes back. Pete from Settle walks through how the platform ties that chain together: a universal product catalog, POs with estimated landed cost, three-way matching, monthly COGS by SKU and location, bill pay, and a working capital line. Stephen Brown handles the accounting questions throughout.

Venture capital available to consumer products fell from around $5 billion to $150 million in three years, and banks were never enthusiastic about inventory as collateral. Greg Russell of BRG Growth Partners walks through what replaced it: short-term secured lenders, term lending, and the fixed fee products that sit on every Shopify and Amazon dashboard. Stephen Brown runs the actual math on three of them live, and an 8% fee turns into 39% APR.
Clean books and a consistent month-end close gave Borboleta reporting they trust, down to exact Amazon discounts, returns, and gross sales. The team now uses those numbers to budget and forecast cash flow.
“I can spend more time making business decisions and not worrying so much about the day-to-day financial records.”: Borboleta
Bank loans, SBA loans, and term lending generally expect solid financials and proven repayment history. Revenue-based lenders are easier to qualify for since they mostly look at sales data, though that ease comes at a much higher real cost.
Read: What lenders look for before they say yesSplit AP into three jobs: one person enters a bill, another approves it, and a third pays it. No one should handle more than one. AP tools like Bill.com or Veem make that separation easy to set up.
Download: Separate AP roles to prevent fraudIt's the time between paying for inventory and getting paid by customers, measured through two supporting formulas: inventory turnover (COGS ÷ average inventory) and days-in-inventory (365 ÷ inventory turnover). Most ecommerce brands land at multiple months. A rising days-in-inventory number is an early sign the cycle is stretching out.
Read: Formulas for measuring your inventory cycleWe use cookies to improve your experience and to measure how our site and ads perform.Read our Cookie Policy