

Whatever pulled you into ecommerce (a product you believe in, a problem you wanted to solve, the freedom of running your own thing), none of it works without the business actually making money. Cash is king.
So, you look forward to those deposits landing. But when they do, does it ever feel like something's missing? Where did the rest of your sales go? How much is your payment processor actually charging you? Is there a glitch on your site? These are all fair questions, and they're exactly what reconciliation answers.
Why you should reconcile deposits
Deposits for ecommerce companies usually come from either your sales channels or from the online payment processors you’ve chosen to use. Sales channels are the sites you sell on. A payment processor is the company that processes credit cards and collects customer payments on your own site.
Deposits from third-party sites like Amazon or Etsy will show in your bank account as coming from that channel. Deposits from your own site, like Shopify, come from whichever processor you've connected. You may have set this up once and never looked at it again, but it’s worth double-checking which processor(s) you're actually using. Reconciling deposits against sales channels and processors will:
- Possibly save you money
- Give you accurate bookkeeping numbers
- Surface valuable insights
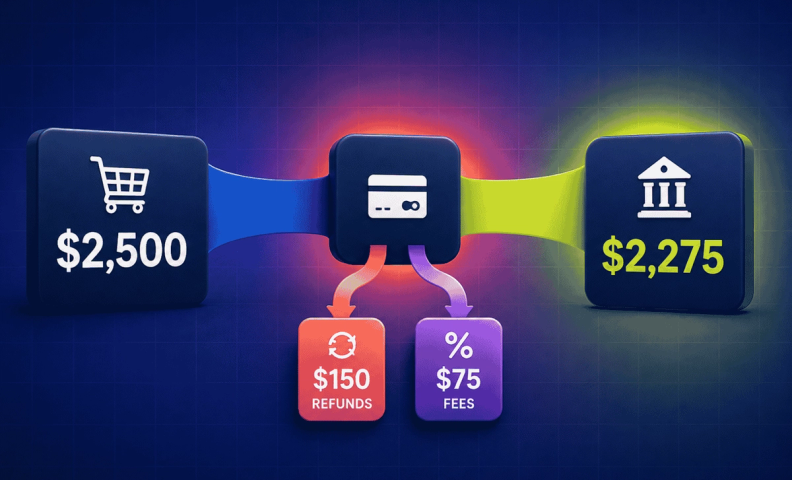
Here's what that gap actually looks like. Say you had 50 orders totaling $2,500 in gross sales this week. Your processor issued $150 in refunds and charged $75 in fees. What hits your bank account isn't $2,500, it's $2,275. If your bookkeeper just records that $2,275 deposit as revenue, you've lost visibility into the $150 in refunds and $75 in fees you'd want to track separately, and your real gross sales number disappears entirely.
For Amazon sellers specifically, see how to record Amazon sales in QuickBooks Online for a channel-specific walkthrough of this exact problem.
Save your business money
We know from experience that reconciling deposits can save real money. You might have a setting on your processor that blocks credit card payments over a certain dollar threshold (we've seen this happen to a client). Sales channels and processors make mistakes you can catch. It's not the norm, but it's worth ruling out.
Read more on accounting for Amazon sellers.
Accurate bookkeeping numbers
Too many owners or bookkeepers see a deposit and simply record that number as revenue. For ecommerce, that's flat wrong, it gives you a false sense of how your business is performing on both the revenue and cost side. Reconciling shows you the true revenue and costs behind everything happening on your channels and processors.
Read more on the unique aspects of ecommerce accounting.
Valuable insights
A thorough reconciliation surfaces:
- Refunds issued
- Discounts given to customers
- Chargebacks won or lost
- Money collected for shipping
- Sales tax liability from collected tax
- Sales channel and processor fees
- Which sales channels are actually most profitable
Reconciling your deposits
Each sales channel and processor reports differently, but here's the general pattern:
1. Initial order reports from sales channels
These show all your orders, fulfilled, canceled, and returned. Look for gross sales (before discounts or refunds) and net sales (what you'd expect from the customer after discounts and refunds, before any processor activity). This starts showing you what's driving net sales down.
2. Settlement reports from online payment processors
These show what's been settled, along with refunds, fees, and chargebacks. The settled amount before refunds, fees, and chargebacks should match what you expected from the sales channel reports. If you have multiple processors, they should add up together. This step confirms your sales channel data is actually flowing through to your processors correctly.
The amount after refunds, fees, and chargebacks is your net deposit, what should show up in your bank account. Note that some processors deduct fees before each settlement. Others batch a month's worth and pull it from your account at the start of the next month.
Red flags worth investigating
A few signs your reconciliation needs a closer look:
- Fees that are a noticeably different percentage than your processor's stated rate.
- Sales channel totals that don't reconcile to processor totals even after accounting for refunds and chargebacks.
- One processor showing all your deposits when you know you're running more than one.
- A settlement report that's missing a period entirely, or shows a gap in dates.
If you want a broader gut-check on your books beyond just reconciliation, our 5 Ecommerce Bookkeeping Warning Signs download covers the other common culprits.
How often should you reconcile?
At minimum, monthly, before you close your books for the period. If your order volume is high enough that a small error could compound for weeks before you'd notice, reconcile weekly instead. This is detailed, repetitive work, exactly the kind of thing that's easy to let slip when you're busy running the rest of your business, which is why it's one of the first things we take off a client's plate.
These reports show you everything happening between your initial orders (gross sales) and what actually lands in your bank account (net sales). Large gaps mean it's time for a deep dive. Smaller ones still hand you the insights covered above. This process is worth your time. You never know what you'll find, and it's exactly the kind of thing that helps you build your business with better numbers.
Frequently asked questions
Why doesn't my bank deposit match my sales channel's reported revenue?
Because the deposit is a net figure, after refunds, fees, chargebacks, and sometimes discounts, not your raw sales. The gap between the two is exactly what reconciliation is meant to explain.
How often should I reconcile my deposits?
At least monthly, before closing your books. Reconcile weekly if you have enough volume that a small discrepancy could snowball before you'd catch it.
What's the difference between a sales channel and a payment processor?
A sales channel is where you sell (Amazon, Etsy, your own Shopify store). A payment processor is who handles the money on your own site. Third-party channels like Amazon deposit directly; your own site's deposits come from whichever processor you've connected.
What are the warning signs that my reconciliation is off?
Fee percentages that don't match your processor's stated rate, sales channel and processor totals that don't line up even after accounting for refunds, one processor showing deposits you know come from multiple sources, or missing periods in a settlement report.
Can I automate this instead of reconciling by hand?
Yes. Tools like A2X can automatically match settlement data to your sales channels, particularly useful for Amazon sellers.
Get expert help reconciling your deposits
If the gap between what you sold and what hit your bank account has never quite added up, that's a fixable problem, and not one you have to solve yourself. This is exactly the kind of detail work our team handles for ecommerce sellers every day, catching the fee errors, missed refunds, and channel mismatches before they cost you money or cloud your decision-making.
